Financial patterns
Financial genogram
Quick answer
What is a financial genogram?
A financial genogram is a multigenerational family map that tracks the financial attitudes, behaviors, experiences, and beliefs that shape how family members relate to money. Pioneered by researchers like Sonya Britt and Brad Klontz in the emerging field of financial therapy, the financial genogram recognizes that our relationship with money is not purely rational but deeply influenced by family history, cultural context, and emotional learning.
Klontz and Klontz (2009) identified "money scripts" as the unconscious beliefs about money that people develop in childhood based on family modeling and experience. These scripts, such as "money is the root of evil," "there will never be enough," or "rich people are greedy," operate below conscious awareness and drive financial behaviors that often seem irrational to the person engaging in them. The financial genogram makes these scripts visible by tracing them across generations.
The financial therapy field
When should you use a financial genogram?
Financial Therapy
Couples Financial Counseling
Family Business Succession
Estate Planning
Financial Literacy Programs
Entrepreneurship Coaching
What goes on a financial genogram?
| Element | What to record |
|---|---|
| Earning Patterns | How each family member earned money: stable employment, entrepreneurship, multiple jobs, disability, dependence on others, illegal income, or inherited wealth. Note career trajectories and satisfaction. |
| Spending Habits | Spending styles across the family: frugal, generous, compulsive, impulsive, strategic, or avoidant. Note major purchases, lifestyle choices, and whether spending matched income level. |
| Debt History | Patterns of debt across generations: mortgages, credit card debt, gambling debts, loans to family members, bankruptcies, and the emotional weight of debt in the family narrative. |
| Financial Secrets | Hidden financial information: secret accounts, undisclosed debts, gambling, financial affairs (hidden spending), inheritance that was concealed, or income that was not reported to the family. |
| Inheritance Dynamics | How wealth was transferred (or not) between generations: who received inheritance, who was excluded, conditions attached to money, family conflicts over estates, and unspoken expectations about inheritance. |
| Entrepreneurship | Family business history: who started businesses, who succeeded or failed, risk tolerance, attitudes toward self-employment, and how entrepreneurship was viewed (admired, feared, or dismissed). |
| Financial Education Level | What each generation knew about money: formal financial education, mentoring about finances, financial mistakes due to ignorance, or sophisticated financial literacy passed down. |
| Money Conflicts | Financial disputes that shaped the family: fights over money, divorces driven by financial stress, family estrangements over inheritance, lawsuits, or sibling rivalries tied to financial inequality. |
| Poverty/Wealth Cycles | The trajectory of family wealth across generations: upward mobility, wealth preservation, boom-bust cycles, wealth dissipation ("shirtsleeves to shirtsleeves in three generations"), or persistent poverty. |
How do money scripts show up on a genogram?
| Money script | Core belief | What it can look like on a genogram |
|---|---|---|
| Money avoidance | "Money is bad" or "I don't deserve money" | Giving money away, unopened bills, a parent who disdained wealthy relatives |
| Money worship | "More money will solve my problems" | Repeated get-rich ventures, debt, a grandparent who equated money with happiness |
| Money status | "My self-worth equals my net worth" | Spending to keep up appearances, hidden debt, shame around a family bankruptcy |
| Money vigilance | "Save, be careful, don't talk about money" | Secret savings, frugality across generations, money managed by one person only |
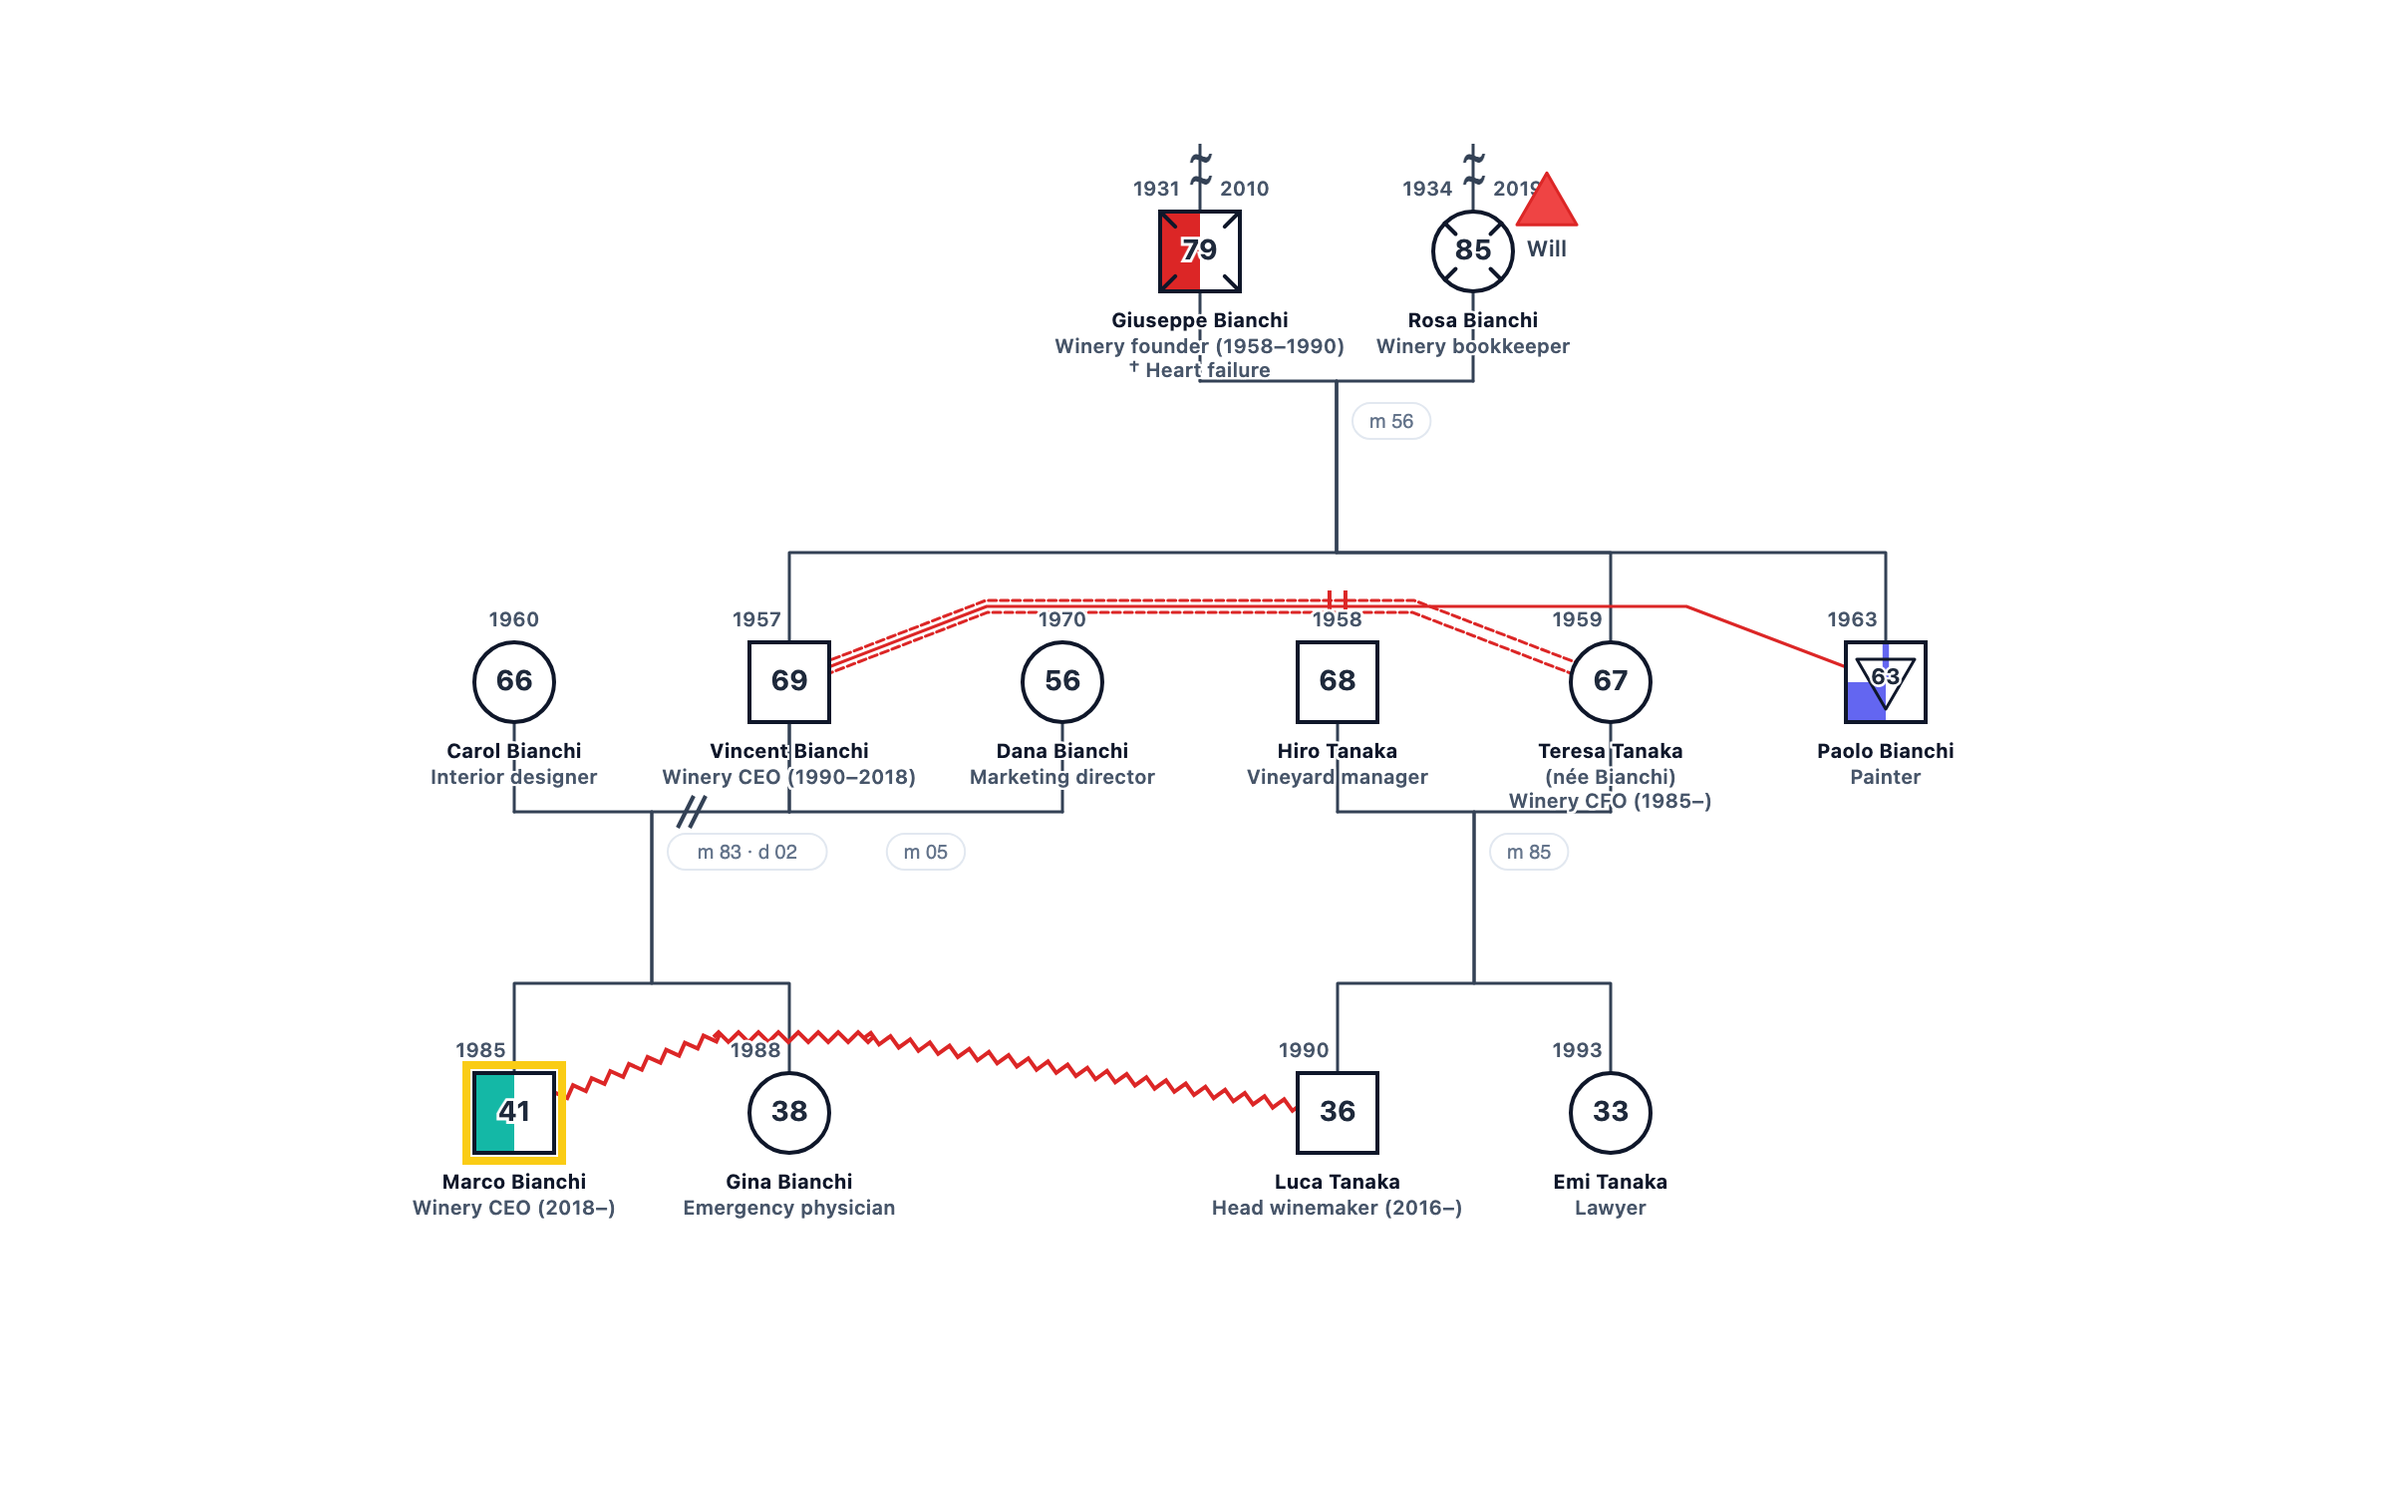
Clinical example: the Bergman family
Fictional composite case for educational purposes
Presenting concern: Rachel (42) and Adam (44) sought couples therapy because their fights about money were threatening the marriage. Rachel described Adam as "irresponsibly generous" and Adam described Rachel as "obsessively frugal." Both earned good incomes, but they could not agree on spending, saving, or charitable giving.
Rachel's financial genogram: Rachel's grandparents were Holocaust survivors who lost everything. Her parents grew up with a scarcity mindset, saving obsessively and viewing any discretionary spending as dangerous. Money was never discussed openly; it was managed secretly by her father. The family money script was: "Everything can be taken away at any moment. Save everything. Trust no one with your money." Rachel inherited this vigilance, maintaining hidden savings accounts her husband did not know about.
Adam's financial genogram: Adam's grandfather was a self-made entrepreneur who believed money should circulate. His father continued this philosophy, generously supporting extended family, donating to charity, and living well. The family money script was: "Money is for sharing and enjoying. Hoarding money means hoarding love." However, the genogram also revealed a shadow side: Adam's uncle had gone bankrupt through excessive generosity and poor boundaries, and the family treated his financial failure as a source of shame.
Therapeutic insight: The financial genogram transformed the couple's fight from "you're cheap" vs. "you're reckless" to an understanding that each partner was enacting a deeply inherited family script. Rachel's saving was an act of survival learned from grandparents who lost everything. Adam's generosity was an expression of love learned from a family that equated sharing with caring. Both scripts had value and both had risks. The couple could now negotiate a financial approach that honored both legacies: adequate savings for security (Rachel's need) and structured generosity (Adam's value), including transparency about all accounts (addressing the secrecy pattern).
| Generation | Rachel's side | Adam's side |
|---|---|---|
| Grandparents | Holocaust survivors who lost everything; vigilance | Self-made entrepreneur; money should circulate |
| Parents | Scarcity mindset; father managed money in secret | Generous to extended family and charity; uncle's bankruptcy treated as shame |
| Couple | Rachel: saver, hidden accounts (vigilance) | Adam: generous spender (avoidance of "hoarding") |
How to create a financial genogram with GenogramAI
- 1
Map family structure and financial context
Build your three-generation family genogram with GenogramAI. For each person, add notes about their occupation, earning level, and general financial situation. Describe money-related events to the AI: business successes, bankruptcies, inheritances, and financial conflicts. - 2
Identify money scripts and behaviors
For each generation, note the prevailing attitudes toward money: saving vs. spending, risk tolerance, financial transparency, views on wealth and poverty, and messages children received about money. Turn on the Social view (in the Views menu) to show each person's socioeconomic class, and add financial details as notes. - 3
Connect patterns to current behavior
Trace how the money scripts traveled from grandparents to parents to the current generation. Note where scripts were adopted wholesale, rejected, or modified. Identify which inherited beliefs serve the client well and which create problems. The genogram becomes a roadmap for conscious financial decision-making.
Frequently asked questions
What is a financial genogram?
A financial genogram is a multigenerational family diagram that maps money-related attitudes, behaviors, and patterns across at least three generations. It tracks earning patterns, spending habits, debt history, financial secrets, inheritance dynamics, entrepreneurship, financial education, and money conflicts. The goal is to reveal the "money scripts" (unconscious beliefs about money) that each family member inherited and how these shape current financial behavior.
What are money scripts and how do they appear on a genogram?
Money scripts are unconscious beliefs about money identified by Brad and Ted Klontz in their financial psychology research. The four main categories are: money avoidance ("money is evil"), money worship ("money will solve everything"), money status ("my worth equals my net worth"), and money vigilance ("save everything, spend nothing"). A financial genogram reveals which scripts dominate each generation and how they were transmitted through family experience and modeling.
Who uses financial genograms?
Financial genograms are used by financial therapists (certified through AFCPE or FTA), financial planners doing holistic client work, family business consultants, estate planning attorneys, couples therapists addressing financial conflicts, and family therapists. In the field of financial therapy, exploring family-of-origin money history with a genogram is a common early assessment step.
How can a financial genogram help couples?
Research has found that arguments about money predict divorce more strongly than other common disagreements (Dew, Britt & Huston, 2012). A financial genogram helps couples understand why they handle money differently by revealing each partner's family money messages. When one partner is a compulsive saver and the other a generous spender, the genogram often shows these are inherited family patterns rather than character flaws, which reduces blame and opens space for negotiation.
What role does a financial genogram play in estate planning?
In estate planning, the financial genogram reveals patterns of inheritance conflict, favoritism, financial secrecy, and money-related family rifts across generations. It helps families anticipate potential conflicts before they arise and make more thoughtful decisions about wealth transfer. It can also surface unspoken expectations and entitlements that, left unaddressed, destroy families after wealth is transferred.
Can a financial genogram reveal poverty cycles?
Yes. Financial genograms are valuable for understanding multigenerational poverty, revealing not just economic circumstances but the beliefs and barriers that perpetuate financial hardship: limited financial education, distrust of financial institutions, survival-mode spending patterns, and lack of models for wealth building. This understanding helps design interventions that address root causes rather than just symptoms.
Further Reading
- Klontz, B., & Klontz, T. — Mind Over Money: Overcoming the Money Disorders That Threaten Our Financial Health. Broadway Books, 2009
- Klontz, B., Britt, S. L., Mentzer, J., & Klontz, T. — Money beliefs and financial behaviors: Development of the Klontz Money Script Inventory. Journal of Financial Therapy, 2(1), 2011
- Dew, J., Britt, S., & Huston, S. — Examining the relationship between financial issues and divorce. Family Relations, 61(4), 615-628, 2012
- McGoldrick, M., Gerson, R., & Petry, S. — Genograms: Assessment and Treatment (4th ed.). W.W. Norton & Company, 2020